From CSRD gap analysis to a first report that holds up.
Omnibus I redrew who reports and when: more than 1,000 employees, more than EUR 450 million net turnover, and the first wave-2 reports in 2028 on FY2027 — under revised ESRS. Habitat's CSRD compliance services take first-timers through a CSRD readiness assessment, a gap analysis against the revised standards, and the writing of the report itself. Not sure you are still in scope? Check the post-Omnibus test in 60 seconds.
Three facts set your timetable.
The CSRD you first heard about in 2023 is not the CSRD you will report under. Since early 2026, three things have been settled — and together they define the runway for every FY2027 first-timer.
Directive (EU) 2026/470, in force since 18 March 2026, limits mandatory CSRD reporting to undertakings with more than 1,000 average employees and more than EUR 450 million net turnover — both tests together. Listed SMEs, the former wave 3, are out of mandatory scope entirely.
Wave-2 companies that meet the new thresholds report for the first time in 2028, on FY2027. For a calendar-year company the reporting year opens on 1 January 2027 — which makes what remains of 2026 the time to build the data, policies and processes the report will draw on.
On 3 July 2026 the Commission adopted the delegated act on revised, simplified ESRS, amending Delegated Regulation (EU) 2023/2772. The revised standards apply mandatorily from financial years beginning 1 January 2027 — so first-timers prepare against the revised set, not the 2023 one.
Details can still move — the revised ESRS were in the Parliament and Council scrutiny period in October 2026 — but the direction is fixed, and waiting for final punctuation is not a strategy. Our post-Omnibus map of the EU ESG rules tracks the moving parts; the sections below cover what to do about them.
From scope check to signed report.
Six services, bought separately or run as one programme. Every engagement is scoped in writing — scope, timeline and price — with a fixed-fee quote within 48 hours.
Most first-timers start with 01 and 02 together: a written scope position, then a gap analysis that turns "CSRD readiness" from a feeling into a task list with owners and dates. And if what you need is simply sustainability report writing services against disclosures you have already mapped, 05 can be bought on its own.
The dates behind your first report.
| Date | What it means for a FY2027 first-timer |
|---|---|
| 14 April 2025 | Stop-the-clock adopted: Directive (EU) 2025/794 postpones wave-2 and wave-3 reporting by two years — the origin of the FY2027 first reporting year. |
| 26 February 2026 | Omnibus I, Directive (EU) 2026/470, is published in the Official Journal; in force 18 March 2026. Mandatory scope resets to more than 1,000 employees and more than EUR 450 million net turnover, cumulatively. |
| 3 July 2026 | The Commission adopts the delegated act on revised, simplified ESRS, amending Delegated Regulation (EU) 2023/2772. As of October 2026 it sits in the Parliament and Council scrutiny period. |
| 1 January 2027 | The revised ESRS apply mandatorily from financial years beginning on this date — for calendar-year companies, the first reporting year opens. |
| 19 March 2027 | Member-State deadline to transpose Omnibus I into national law. Until transposition lands, the position under old national rules can differ by country — one more reason to fix your scope position in writing. |
| 2028 | Wave-2 companies that meet the new thresholds publish their first CSRD reports, covering FY2027. |
Status as of 31 October 2026. Sources: Directive (EU) 2025/794; Directive (EU) 2026/470 (OJ 26 February 2026); Commission delegated act on revised ESRS, 3 July 2026.
The hardest disclosures are numbers.
Narrative disclosures can be drafted in the final quarter; data cannot. The quantitative core of a first CSRD report rests on measurement work that takes months — above all a greenhouse-gas inventory built to the GHG Protocol Corporate Standard, with Scope 1, Scope 2 reported both location- and market-based, the Scope 3 categories that matter for your value chain, and country-specific emission factors behind every figure.
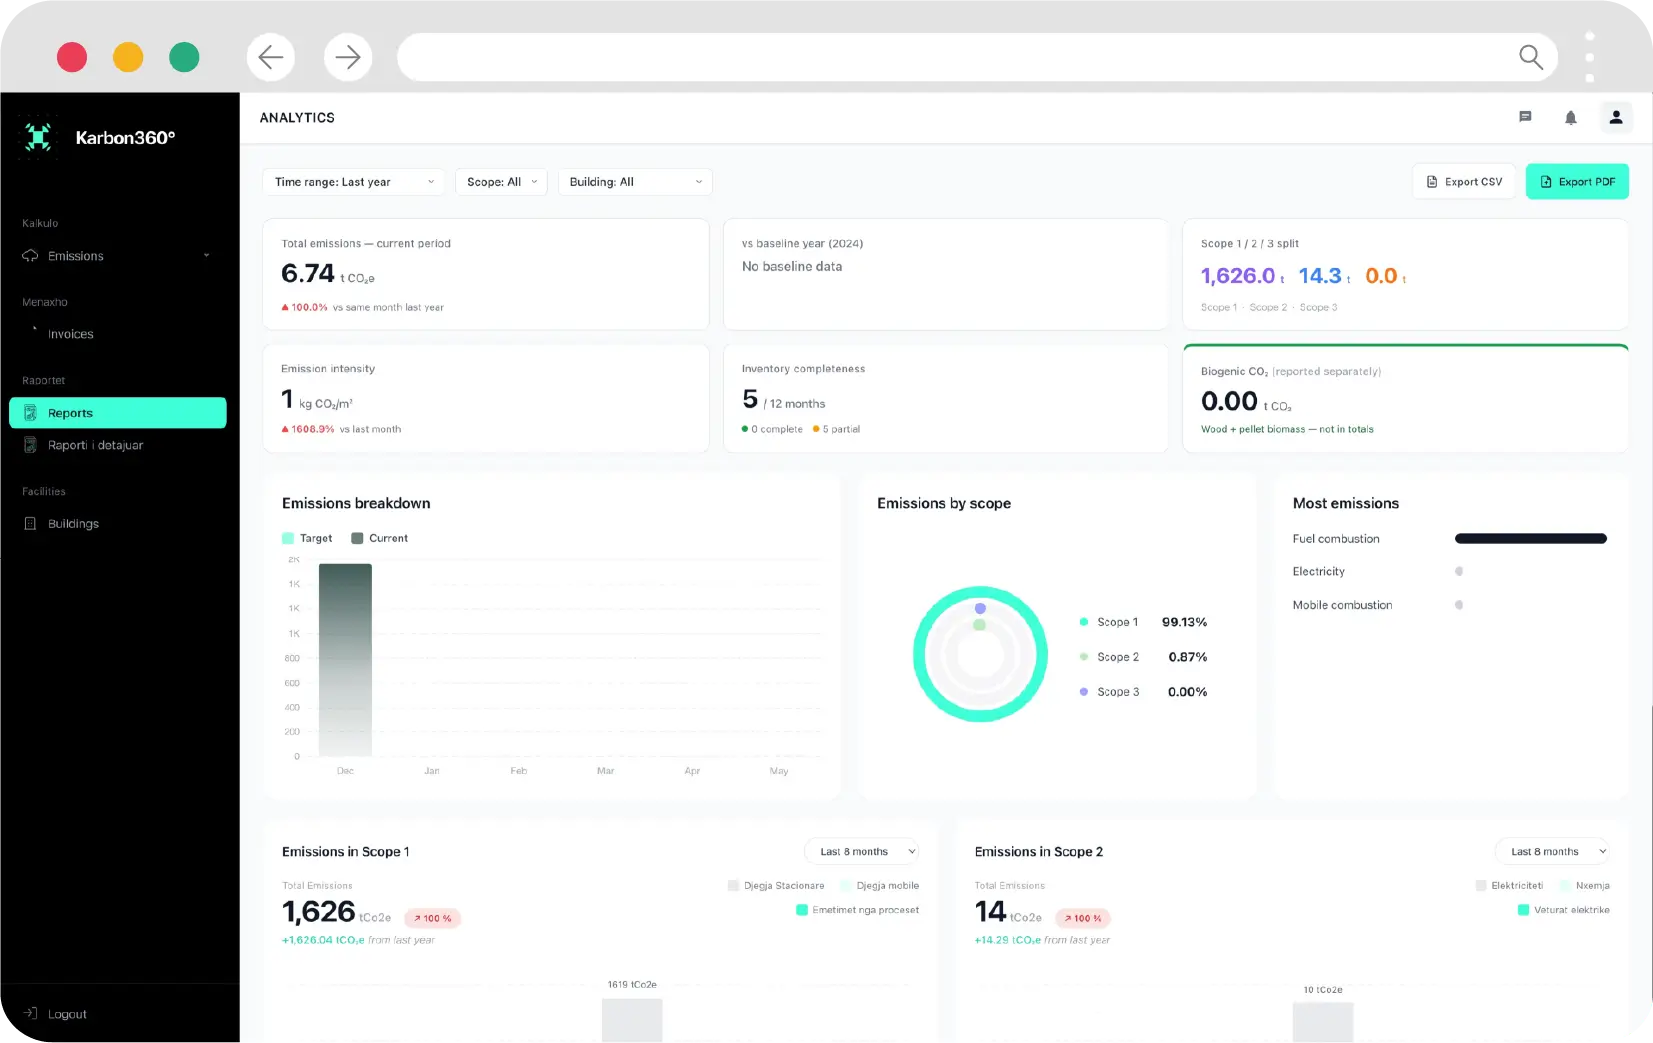
That is why the gap analysis comes first. It tells you which datapoints you already hold, which exist but cannot be evidenced, and which require new measurement — in time to fix the third category before the reporting year starts. The inventory work runs in Karbon360°, our own platform, so every figure in the final report carries its calculation and evidence trail with it rather than living in a spreadsheet no one can defend.
Karbon360°
Karbon360° transforms energy and business activity data into structured greenhouse-gas inventories — Scope 1, 2 and 3 calculations, country-specific emission factors and the audit trail your assurance provider will ask for behind every figure.
A gap analysis that does not end in owners and dates is a reading exercise.
Out of scope, still in the chain.
After Omnibus I, most mid-size companies are outside mandatory CSRD scope — and will still feel the directive through their customers. In-scope groups must report on their value chain, so the datapoints they owe their auditor become the questionnaire in your inbox. A CSRD readiness assessment for suppliers is deliberately smaller than the full exercise: identify which of your customers report, which datapoints they will ask you for, and build those first — usually starting with the carbon inventory. The EU has also capped the cascade: the VSME standard, annexed to Commission Recommendation (EU) 2025/1710, is designed as the limit on what large companies and banks should request from SME suppliers, which makes a VSME report the efficient answer to most of what arrives.
CSRD also reaches beyond the EU directly: a non-EU group comes into scope through an EU net-turnover test of EUR 450 million under Directive (EU) 2026/470, and non-EU suppliers to in-scope groups meet the directive through value-chain data requests even when no legal duty names them. For exporters in the Western Balkans the practical sequence is the same whichever trigger arrives first — CSRD questionnaire, bank ESG form or CBAM data request: measure once, to a recognised standard, then reuse the numbers everywhere. That is the logic of our ESG consulting work in Kosovo and across the region.
Frequently asked.
What is a CSRD readiness assessment?
What does a CSRD gap analysis cover?
Who has to report under CSRD after the Omnibus?
What changed in the revised ESRS 2026?
Does CSRD apply to non-EU companies and suppliers?
How long does CSRD readiness take for a first-time reporter?
FY2027 is written in 2026.
Tell us where you stand — clearly in scope, near the thresholds, or on the receiving end of a customer's questionnaire. We come back within 48 hours with the right starting point and a fixed-fee quote in writing.